Banking News – The Inland Revenue Department has issued the “Skill Development Fee Related Procedure, 2083” to make the administration of the skill development fee levied on the sale of gold and silver jewelry and items simple, organized, and effective. In Section 14 of the Finance Act, 2083, there was a provision to levy and collect a skill development fee on the sale price when selling gold, silver, and their jewelry and items to consumers in Nepal. According to the same provision, the Department has issued the procedure covering arrangements related to fee administration, collection, deposit, transaction accounting, submission of details, testing, and appeals, informed Keshav Raghuvanshi, Information Officer of the Department.
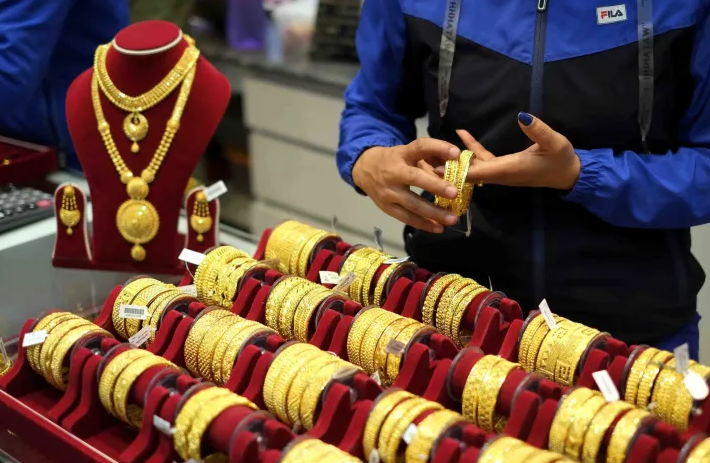
According to the procedure, a 0.05 percent skill development fee will be levied on the sale price when selling gold or gold jewelry and items and silver or silver jewelry and items for consumption in Nepal to the final consumer. Such a fee must be collected at the time of selling the item. The procedure has also made arrangements ranging from issuing invoices to accounting for transactions and submitting monthly statements. Businesses conducting transactions subject to the skill development fee must issue invoices in the prescribed format. Transaction accounting must be done on an accrual basis, and monthly statements must be submitted to the concerned revenue office within the 25th of the following month, whether or not there were transactions in each month.
There is a provision for an additional fee equal to 0.05 percent per day of the skill development fee applicable for failure to submit statements within the specified time or Rs 1,000 per statement, whichever is higher. When transporting gold, silver, and gold and silver jewelry or items from one’s shop to a craftsman for jewelry manufacturing and from the craftsman to the place where the business is operated, a challan in the prescribed format stamped by the concerned office must be kept along with it. The craftsman making such jewelry must mandatorily have a Permanent Account Number.
The procedure has also clarified the situation of purchasing old gold, silver, and gold and silver jewelry and selling new jewelry to the same customer. When purchasing old jewelry from a customer and selling new jewelry to the same customer up to the value equal to the weight of the old jewelry, no skill development fee will be levied. However, if new jewelry is sold by adding to the old weight, the skill development fee must be collected on the value of the added gold or silver and the entire labor and wastage charges.
When the general public sells gold, silver, or gold and silver jewelry to a businessperson, a copy of their identity-revealing citizenship, national identity card, driving license, Permanent Account Number certificate, or other identity card issued by the Government of Nepal must be mandatorily submitted. There is a provision to submit proof of purchase of the gold, silver, or jewelry being sold. If the gold and silver was brought from abroad, its proof must also be shown.
According to the procedure, every gold and silver businessperson must also keep a notice board in the prescribed format in their shop. Similarly, businesspersons must deposit the skill development fee collected from consumers under the concerned office’s code and revenue heading number 11413 within the 25th of the following month. There is a provision for 15 percent annual interest for failure to deposit the fee within the specified time. The procedure provides that if evasion of the skill development fee is found during transaction testing, the tax officer may determine the fee. If any businessperson fails to collect the fee, splits sales transactions, declares lower transactions than actual and collects less fee, or is found evading the fee through any other means, an additional 25 percent fee will be levied on the determined fee.
 About Us
Comment